How to Access Property Records in Arizona

Property records in Arizona are essential to residents and the government agencies that create, maintain, and hold them. Realtors, title companies, attorneys, the courts, and other professionals use these documents in many different situations. Arizona property records pertain specifically to Arizona properties, and affect real estate deals, estate planning, taxes, foreclosures, and other property-related issues.
You can search for these public records in various ways, such as:
Government Sources
Various offices maintain real estate records in Arizona.. For example, the county recorder's office is where you would file deeds, mortgage certificates, liens, surveys, etc. You can contact the county treasurer's office if you are searching for tax information or assessments. The Arizona Department of Revenue oversees all county treasurers' offices.
 Online
You can easily access public property records through the county recorder's office in Arizona.. You may be able to search the county recorder's office website for records. Viewing these records is free, but printing copies is not. Pinal County has a portal where you can search for dozens of different types of public property records. Some other county recorder websites include:
Property data has been recorded for a very long time. Some governments move their historical property records into physical or online archives so you can still find them from a different location, and may have to access paper documents.
 In Person
You can look up the county recorder's office address, visit during office hours, and request copies in person. The Arizona Secretary of State has created a list of all the county recorders in the state.
 Commercial Sources
Commercial services make it easy to find property and related records quickly and easily. PropertyChecker.com offers nationwide property searches. You can search by address, parcel ID, owner's name, phone, or email.
Land Records in Arizona
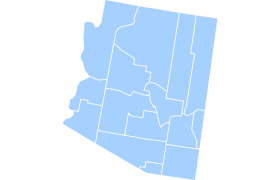
You can find land records in Arizona with any of the 15 independent county recorders' offices. Arizona does not use a centralized state database for its land records. County recorders are responsible for storing and permanently preserving deeds, deeds of trust, liens, mortgages, and subdivision plat maps. The Arizona State Land Department manages and tracks information on state-owned parcels, leases, permits, and State Land Trusts. You can find additional land information through county assessors, who can provide supplemental data regarding parcel boundaries, property valuations, and tax rolls.
Rather than a state-level registry, Arizona uses a county recording system. These government offices simply accept and record transfer documents (like deeds). Most land deeds in Arizona are not organized merely by street addresses, but by exact grid coordinates from a baseline meridian. This system divides the state into a checkerboard of square miles (sections) based on their relation to the initial survey point. Because there is no single statewide portal, each county provides its own localized search tools. Larger counties like Maricopa offer dense databases that provide online information on deeds, maps, and document images dating back to the late 1800s.
Plat maps are also readily available online through the county recorder's office websites. Checking a plat is crucial for vacant or rural land, as it provides legally binding details that standard tax maps often miss. Plats detail designated rights-of-way, roadways, and utility easements (crucial for remote parcels). Plats can help prevent the purchase of landlocked rural properties.
To find historical land records older than 1800, check with the Arizona Bureau of Land Management (BLM) General Land Office. You will find land that was transferred between the federal government and private owners (homestead entries, cash sales, or military warrants). For subsequent transfers, use the county recorder's office. Use the Bureau of Land Management (BLM) General Land Office to search, view, and download millions of federal land patents, survey plats, and field notes. For Master Title Plats, historical indices, and original land document microfiche, visit the BLM Arizona State Office Public Room in Phoenix.
For deep historical research on Spanish and Mexican land grants or territorial maps, check the state's archive repositories. Located in the Polly Rosenbaum Archives and History Building in Phoenix, the Arizona State Library, Archives, and Public Records holds early territorial maps, Sanborn Fire Insurance maps, and historic land grant records. You can also find a treasure trove of territorial property maps and regional collections through the Arizona Memory Project.
What Are Property Records?

Property records are documents (both legal and unofficial) that contain information about real property and its owner(s). Some reports perform functions such as appraisals, which assess value, or deeds, which transfer ownership.
What Information Can You Find in Arizona Property Records?
When searching property history data, you can find extensive details across all areas of Arizona. Some of the information contained in Arizona property records includes:
-
 Liens
-
 Tax Records
-
 Ownership History
-
 Mortgage / Loan Records
-
 Foreclosures
-
 Plat Maps
-
 Easements / Conveyances
-
 Property Details
-
 Zoning
-
 Building Permits
-
 Boundary Lines
-
 Assessed Values
-
 Deeds
-
 And More!
Who Looks Up Arizona Property Records and Why
Many different people and businesses use property records for various reasons. Some of the most common use cases in Arizona are as follows:
-
 Homebuyer - Although most homes in Arizona are affordable (average price - $428,000), a typical homebuyer pulls up property records to examine the ownership history, value, taxes, and amenities to see whether it belongs on their short list.
-
 Investor - An investor who knows that Phoenix has evolved into a luxury market wants to invest in a foreclosure listing they see online. They use property data to check for liens, bankruptcies, property values, and any obvious title issues.
-
 Appraiser - With rising inventory in Arizona, appraisers can use property records to check out comparables in the neighborhood, comparing square footage, amenities, taxes, values, and neighborhood details to build their report.
-
 Neighbor - With new home sales on the rise in Arizona, neighbors may want to check out properties to see whether upgrading might be an option or investigate the ownership history of nearby properties to ensure their family's safety.
Types of Property Records in Arizona
As you search through Arizona property reports, you will find many different types. The most common ones you will come across are listed below.
Deeds and Conveyance Records
Deeds transfer property ownership and also verify who legally owns a home. Some of the information contained within deeds includes:
- Name of the Seller/Grantor and Buyer/Grantee.
- A detailed description of the property.
- Maps and plats, along with boundaries and sometimes surveys, show the acreage and edges of the property.
- Conveyance language explaining the ownership transfer from one person or entity to another.
- Notarization and execution are at the bottom, where everyone signs to make it legal.
Conveyance records accompany deeds by specifically stating who is giving up the property and who will take it over.
Property Tax Records
Anyone who owns real estate in Arizona must pay annual taxes. Arizona's median property tax rate is 0.51%. The average homeowner pays only $1,707 in taxes per year.
A typical property tax record in Arizona contains:
- Property Information - A tax record contains basic information about the property, such as the address and parcel number.
- Assessment Details - The documents show the property's assessed value.
- Tax payment History - The document includes the owner's tax payment history.
- Exemptions and Deductions - The records may note exemptions or deductions that apply to the land.
- Owner Information - The report shows the owner's name with their contact information.
- Liens - Property tax records often show delinquencies and outstanding taxes.
- Tax Rates - Tax records may indicate applicable tax rates for the area or county.
How Often is Property Tax Assessed in Arizona?
Property tax assessment is under the Arizona Department of Revenue. Each year, real property gets assessed and valued. The basic process goes as follows:
- Data collection - The assessor collects information about the property, noting its size, location, amenities, and condition.
- Valuation - The local assessor determines the property's assessed value.
- Notice of value - The assessor then sends the property owners a notice of value.
- Appealing - If the owner disagrees with the assessment value, they may appeal.
using our property tax calculator.
Property Liens and Encumbrances in Arizona
Encumbrances such as liens can drastically affect a home. There are two basic types of liens: voluntary and involuntary.
Voluntary Liens
Voluntary liens are those that you choose and allow. Examples include mortgages, lines of credit, and home equity loans, where you use your home's value as collateral for a loan.
Mortgage Liens - Mortgage liens are very common. Whenever you cannot afford to pay cash for a house, you can take out a mortgage. If you default, the lender can seize and sell your home to pay off the loan.
Mortgage documents in Arizona contain information such as:
- Property Description - The mortgage specifies the property details under the loan.
- Prepayment Penalty - Some mortgages include a prepayment penalty clause.
- Escrow Accounts - The mortgage may require an escrow account for homeowners' insurance and property taxes.
- Loan Amount - The document shows the principal loan amount.
- Parties Involved - The mortgage identifies the lender and the borrower.
- Repayment Terms - A mortgage document establishes the repayment terms.
- Default and Foreclosure - The document specifies the conditions under which the loan is considered in default.
Involuntary Liens
Involuntary liens are those that you do not choose or allow. You could lose your house through an involuntary lien if you owe a debt. Some examples of involuntary liens are:
- Mechanic's Liens - If a contractor, material supplier, or landscaper works on your property and you do not pay them, they can place a lien on the property.
- Tax Liens - If you fail to pay your annual property taxes, the local government will put a tax lien on your property.
- Judgment Liens - If you owe a debt to a creditor, they can sue you in court, and if they win, place a lien on the property, eventually foreclose, and sell it to get paid.
The Process of Property Liens in Arizona
The following is the standard process for putting a lien on a property in Arizona:
- The creditor must provide the homeowner with a Notice of Intent before obtaining the lien.
- The creditor prepares the lien form, including property details, the owner's name, and the claim amount.
- The creditor then files the lien at the county recorder's office.
- After filing, the creditor may take legal action to enforce the lien if the borrower fails to pay. That action is to foreclose and sell the property at auction.
Easements and Covenants
Easements often appear in property records, such as deeds, outlining certain rights of way. A right-of-way gives someone other than the owner access to the land. A good example might be a government agency that uses part of someone's land for a parking lot or storing materials. Any government officer can enter the land to maintain their property or equipment without first asking the owner.
Covenants are rules dictating how the land may be used. You will see these in condo developments and private gated communities with shared common grounds. The rules specify how an owner may or may not use the land. For example, most covenants want to maintain the look and value of each property so they may prohibit boats, motorcycles, or broken-down cars on the property.
Plats and Surveys
Plats and surveys are both types of maps. Plats show boundaries from neighboring parcels, while surveys only show the boundaries of a single parcel.
Property surveys contain information such as:
- Property Description - The survey provides a legal description of the property, including its boundaries, dimensions, and other relevant information.
- Boundary Lines - The document depicts the exact location and shape of the property through boundary lines.
- Markers - Surveys show markers and monuments on or near the property.
- Topographic Features - Surveys may include natural features, elevations, and contours present on the property.
Property Descriptions and Boundaries in Arizona
Legal property descriptions use landmarks and other details to describe the parcel so that anyone reading them can identify the correct property. Surveys and land measurements display a parcel's proper boundaries. Boundary disputes erupt when someone believes another person is encroaching upon their land.
Foreclosures
Foreclosure records are also essential. Sometimes, investors look for distressed homes in foreclosure to buy cheaply and sell for a profit.
Arizona Pre-Foreclosures for Investors
In Arizona, a primarily non-judicial state, lenders file a Notice of Default (NOD) at the county recorder's office where the property is located. That signals a pre-foreclosure. It is typically filed after the borrower misses 30-90 days of payments. During the pre-foreclosure window before the auction/sale, investors can research the property and prepare to purchase it.
Investors have roughly 90 days to take action. Ninety-one days after the NOD, the lender can legally notify the borrower via a Notice of Trustee's Sale that the auction has been set. The Notice of Trustee's Sale details the auction's date, time, and location.
Foreclosures (Trustee Sales) mostly occur daily, Monday through Friday. Specialized sales, such as tax liens and surplus property, are held either annually in February/March or monthly, depending on the county.
Trustee/foreclosure sales begin with the lender's opening bid (typically the unpaid mortgage balance plus fees). The winning bidder must pay the full amount generally in cash or by certified check (often by 5:00 p.m. on the day of the sale or the next business day).
In counties with tax liens and deed sales, when taxes are unpaid, the county treasurer holds an annual public auction of tax lien certificates. Investors bid on the lowest interest rate they are willing to accept on the debt (starting at 16%).
If the property owner does not redeem the lien within three years, the lienholder may foreclose on the property. If a tax lien goes unsold, the county can seize the property and eventually sell it at a Tax Deed Sale.
Many counties have transitioned tax deed and surplus property auctions to online platforms. However, the majority of traditional bank/trustee foreclosure sales in Arizona still require buyers to attend in person at the county courthouse.
If you attend a physical auction, you must pay in cash or by cashier's check on the spot. However, online county auctions generally require you to pay upfront registration deposits (e.g., $250 or a percentage of the expected bids) via ACH.
In tax-deeded surplus land sales, counties like Maricopa County and Graham County stipulate that winning bids at Board of Supervisors auctions are still subject to final review and acceptance by the county Board.
What makes Arizona distinctive is that it has one of the fastest non-judicial foreclosure processes in the U.S. Another unique feature is that Arizona offers borrowers strong protections in certain situations. In non-judicial foreclosures, most Arizona home loans are secured by a Deed of Trust rather than a standard mortgage. Lenders foreclose through a "Trustee's Sale," which does not require them to file a lawsuit. A neutral trustee conducts the foreclosure on behalf of the lender.
The non-judicial process takes 90 to 120 days from the initial notice to the actual public auction of the property and follows these distinct stages:
1. Pre-Foreclosure (Notice of Default): Foreclosure begins after a borrower misses payments for more than 120 days. The lender or an appointed third-party trustee will record a "Notice of Default" in the county recorder's office and mail it to the homeowner.
2. Notice of Sale (NOS): If the borrower does not bring the loan current, the trustee records a Notice of Trustee's Sale. By Arizona law, the sale date must be at least 91 days after this notice is recorded. The trustee must also:
- Mail a copy of the NOS to the borrower by certified or registered mail within five business days of recording.
- Post a notice on the property at least 20 days prior to the sale.
- Publish the notice in a local newspaper once a week for four consecutive weeks.
3. Reinstatement Period: Homeowners in Arizona have the legal right to "reinstate" their loan (pay all past-due amounts, late fees, and legal costs) up to one business day before the scheduled trustee's sale (up to 5:00 p.m.). Doing this stops the foreclosure completely. Homeowners cannot reclaim their property after the auction is complete.
4. Trustee's Sale (Auction): On the day of the sale, the property is sold at public auction for cash. The highest bidder must pay the purchase price, typically by 5:00 PM the following business day. If there are no outside bids, the lender takes ownership of the property, and it becomes Real Estate Owned (REO).
5. Post-Sale & Eviction: In Arizona, homeowners do not have a post-sale "right of redemption" (the ability to buy the home back after the auction) in a non-judicial foreclosure. If the former homeowner does not voluntarily vacate, the new owner must file a "Forcible Entry and Detainer (FED)" action (eviction) through the local justice court to legally remove them.
The entire process can often be completed in approximately 4-6 months after default, though timelines vary depending on the circumstances.
Arizona is also well known for its anti-deficiency laws, which can protect homeowners from owing additional money after the foreclosure. The lender may be prohibited from pursuing the borrower for any remaining loan balance after a trustee's sale if:
- The property is 2.5 acres or less.
- It is used as a single-family or two-family dwelling.
- And it meets the other statutory requirements.
These protections are stronger than those in many other states, although they do not apply in every situation (such as investment properties, commercial properties, or certain refinanced loans).
Another final caveat is that if the foreclosure sale generates more money than is needed to pay the foreclosing lender, junior lienholders, and allowable foreclosure costs, the homeowner or other entitled parties may claim the remaining funds.
Buying and Selling Property in Arizona

Property records are most often used in real estate transactions. When you buy real estate in Arizona, you must learn as much as you can about it beforehand. When selling real estate in Arizona, you must disclose any material defects you know about to the buyer.
Whenever you take out a mortgage, you must purchase title insurance. The closing company or attorney handling the sale will perform a title search for you.
How Property Transfer Works in Arizona
Most property changes hands in Arizona through real estate sales. The property is legally transferred through a recorded deed. Unlike many other states, Arizona does not impose a real estate transfer tax on the sale or conveyance of property. However, when recording a deed with the county recorder's office, you will need to pay the fee (typically $30 per document).
Transfer-on-Death Deed
Arizona uses a Beneficiary Deed (authorized under A.R.S. § 33-405) in lieu of a Transfer-on-Death (TOD) deed. This document allows you to name a beneficiary who will automatically inherit your property upon your death, completely bypassing the probate court system. During your lifetime, the beneficiary has zero rights to the property. You retain full ownership, can sell or refinance the home, and can revoke or change the deed at any time. Most people hire an attorney to draft and record a Beneficiary Deed, which typically costs between $150 and $500. However, the property transfer is subject to any outstanding debts the deceased owed at the time of their death. Beneficiaries might have to deal with additional creditor claims that could have been resolved if the estate had gone through probate.
Probate (Transfers without a TOD)
If a property lacks a clean, valid transfer document (such as a Beneficiary Deed, trust, or joint tenancy), it must go through probate court after the person passes away. During probate, a court-appointed personal representative (executor) assesses the deceased's assets, settles their debts and taxes, and distributes the remaining property. Probate in Arizona is notoriously expensive and time-consuming, typically costing $5,000 to $30,000 depending on the estate's complexity, and taking 6 months to over a year to resolve. For smaller, less complicated estates (where real property is valued under $300,000 and personal property is under $200,000), heirs can skip formal probate and use an affidavit to claim the real estate after six months.
Intestate (Dying without a Clean Transfer)
If an Arizona resident dies without a will or an alternative transfer method, Arizona's intestate succession laws decide exactly who gets their property. If the person is legally married, their spouse typically inherits everything, particularly if they have no children or all of their children are also their children. If the deceased has children from another relationship, their spouse splits the estate with them. If they are unmarried, the estate passes down to their descendants (children and grandchildren), then to their parents, and then to their siblings. Friends or charities are completely excluded. If no blood relatives can be located, the property ultimately becomes the property of the State of Arizona.
Why Property Values Are Important in Real Estate Transactions
One of the most vitalaspects of buying or selling property is knowing its fair market value. You can consult appraisals and tax assessments to get an accurate accounting of the value.
The average home value in Arizona is approximately $417,708. Tax professionals use assessments to value real estate and set the tax rate.
What Factors Determine Property Values in Arizona
The following factors influence higher home values in some cities of Arizona:
-
 Proximity to Convenience - Areas closer to restaurants, shopping centers, and transportation networks fetch higher values.
-
 School Districts - Good school systems significantly increase a home's value.
-
 Neighborhood - Neighborhoods with low crime rates and positive development often have higher values.
-
 Size - Homes with bigger or more exterior space often command a higher price.
-
 Zoning and Regulations - Zoning laws and other regulations can affect a home's value..
Arizona Flood Zones
In Arizona, flood zones are usually caused by sudden monsoon thunderstorms rather than coastal tides. High-risk regions are usually near dry washes, arroyos, and floodplains. If a home falls into a high-risk FEMA zone, federally backed mortgages require flood insurance, making it important for buyers to check the flood status before closing.
While you might not associate the desert with flooding, seven of Arizona's 15 counties are rated high for inland flood risk. Due to Arizona's specific topography, dry deserts can quickly become raging rivers of runoff during a summer storm. Areas of central Arizona, specifically older sections of Phoenix with less developed urban runoff systems, can be prone to flash flooding.
FEMA categorizes flood risk using maps called Flood Insurance Rate Maps (FIRMs) using the following designations:
- Zone A: High-risk areas near lakes, rivers, or streams where base flood elevations (BFEs) haven't been determined.
- Zone AE / A1-A30: High-risk areas with a determined BFE, utilizing detailed hydraulic analyses.
- Zone AO: High-risk areas subject to shallow and unpredictable sheet flooding (usually depths of 1 to 3 feet), commonly found on sloping terrain.
- Zone AH: High-risk areas subject to shallow flooding with pond depths of 1 to 3 feet.
- Zone V / VE: High-risk coastal areas subject to velocity hazards (storm surge and aggressive wave action).
High-Risk Zones (Zones A, AE, AO) have a 1% or greater chance of flooding in any given year (also called the 100-year floodplain). Federal law mandates that if you have a federally backed or insured mortgage, you must purchase flood insurance. Moderate- to Low-Risk Zones (Zones X, B, C) have a reduced or minimal risk of flooding. In these areas, flood insurance is optional, but experts highly recommend it. In fact, FEMA notes that about a third of all flood insurance claims come from outside high-risk zones.
Be aware that FIRMs can be updated as the climate changes and, along with it, a property's flood zone rating.
Standard homeowners' insurance policies in Arizona do not cover flood damage. Therefore, buyers need to be proactive and check the FEMA map using the exact property address to identify its specific flood zone designation.
During the escrow process, your mortgage lender will order a formal flood zone determination. Do not wait until the last minute to find out whether this comes back as high risk. If the home is in a high-risk zone (Zone A/AE), ask if the seller has an Elevation Certificate. This document measures the lowest point of your home relative to the estimated flood level and can save you thousands of dollars on annual insurance premiums. Reach out to an Arizona-licensed insurance agent to get a dedicated flood policy quote well before your financing contingency period ends. Rates vary widely depending on the zone and the home's elevation.
In terms of flood insurance, the National Flood Insurance Program (NFIP) is a federally backed program managed by FEMA, while private flood insurance is underwritten by independent, for-profit insurance companies. The NFIP guarantees coverage for anyone in a participating community, whereas private insurers assess individual property risk using advanced mapping and may deny coverage to high-risk homes.
- NFIP: Offers standardized coverage. Building coverage is capped at $250,000 for residential properties, and contents are capped at $100,000. It also does not cover temporary living expenses or finished basements. NFIP uses government-standardized rating structures (such as Risk Rating 2.0). It is often more affordable for homes in high-risk zones, but may be overpriced for homes in historically safe zones. It typically requires a strict 30-day waiting period before the policy takes effect.
- Private Flood Insurance: Highly customizable with much higher limits, often exceeding $500,000 for buildings. Private policies can easily be tailored to include temporary living expenses (Loss of Use), swimming pools, and basement contents. With private flood insurance, premiums are based strictly on the specific risk of the individual property, often using AI and predictive modeling to determine risk. In lower-risk areas, private flood insurance is frequently much cheaper than an NFIP policy. Private flood insurance also offers much faster activation times, usually ranging from 7 to 15 days, and occasionally no waiting period when purchased at the time of a new home closing.
Local Rules, Timelines & Fees
Real estate laws vary widely by state. Some of the most common questions asked about rules that apply to property transactions in Arizona, and the answers are as follows:
Standard Closing Timelines in Arizona
- What are the standard closing timelines in Arizona? Most financed purchases take 30 to 45 days to close, while all-cash deals can close in as little as 7 to 21 days. Under the standard Arizona REALTORS Contract, buyers typically have a 10-day due diligence period to conduct inspections and submit repair requests.
Foreclosure Type and Timeline
- Is Arizona a judicial or non-judicial state? Arizona is mostly a non-judicial foreclosure state. If your mortgage or Deed of Trust contains a "power of sale" clause, lenders can bypass the court system to foreclose and sell the property. However, lenders do have the option to pursue a judicial (court-ordered) foreclosure, though it is rarely used.
- What is the typical timeline from filing a foreclosure to auction? In Arizona, the typical timeline from the official filing of a foreclosure (recording the Notice of Trustee Sale) to the auction is 90 to 91 days. This process is almost exclusively handled non-judicially through a Trustee's Sale rather than a court lawsuit.
Redemption Periods
- Does Arizona allow the owner to reclaim the property after the sale? Yes, Arizona allows the owner to reclaim their property after a sale, but it depends entirely on the type of foreclosure process used.
- How long is the redemption period, and under what conditions can the property be reclaimed? If the lender sues the person in court to foreclose, Arizona law grants them a six-month redemption period after the sale. They can reclaim the property by paying the full sale price, plus interest and legal fees. This can be reduced to 30 days if the property was abandoned. If the property was foreclosed on out of court (the most common method in Arizona), they do not have the right to redeem or reclaim the property after the auction ends.
Lien Deadlines & Priorities
- What is the lien filing and foreclosure deadline in Arizona? In Arizona, the deadline to file (record) a mechanic's lien is 120 days from the project's completion, or 60 days if a Notice of Completion is recorded. To enforce the lien, you must file a foreclosure lawsuit within 6 months of recording it. For mortgage liens, a lender must initiate a foreclosure within 1 to 120 days after missed payments.
- What are Arizona's lien attachment rules regarding HOAs? In Arizona, an HOA lien automatically attaches to a property as soon as an assessment becomes past due. The HOA is not required to record a formal document with the county for the lien to be valid. The delinquent assessment balance must be over $1,200 and at least 1 year overdue before the HOA can foreclose (A.R.S. §33-1807 for planned communities, or A.R.S. §33-1256 for condos). The HOA must send the homeowner a 30-day advance notice of intent to initiate collection proceedings via certified mail, return receipt requested. The HOA's lien has super-priority over most other liens and encumbrances, though it remains subordinate to recorded first mortgages, property taxes, and government assessments.
Deeds and Transfer Costs (Recording Fees and Transfer Tax)
- What does it cost to record a deed? The standard flat fee to record a deed in Arizona is $30 per document in most counties. Affidavit of Property Value forms, which are generally required when transferring real estate, are usually included in this recording price. Additional charges may include notary fees ($10), document preparation ($150-$300), and specific county fees.
- Is there a documentary stamp tax or transfer tax? Arizona does not impose a state-level real estate transfer tax or documentary stamp tax. Property sales are completely exempt from all state-level conveyance taxes, though buyers will still need to pay standard recording fees to make the deed public.
Keep in mind that fees and timelines change, so always verify the timelines and costs with the county clerk before filing.
Maintaining and Amending Arizona Records
Part of maintaining property reports is amending them when there is an error or a change in life situation.
If your property records contain errors, you can correctthem by contacting the proper office and requesting a change.
When someone dies, public property data needs to be updated. Take the death certificate and the new deed and file them with the county recorder's office.
You may want to change the name on your property data if you get married or divorced. Visit the county recorder's office and bring your marriage certificate or divorce decree.
The Role of the County Recorder

Every county has a recorder's office, responsible for filing, maintaining, storing and making certain documents available upon request., How to Ensure Data Privacy for Property Records
It's perfectly legal to access public property records without a reason. Data transparency exists to prevent government agencies from having too much power over the people.
You cannot remove all your information from public filings. However, you can contact the offices that hold your records and ask them to remove any additional details, such as your email address and phone number.
- 6751 N. Sunset Boulevard Suite 320,
Glendale, AZ 85305 - (602) 610-2857
Instant Access to Arizona Property Records
- Owner(s)
- Deed Records
- Loans & Liens
- Values
- Taxes
- Building Permits
- Purchase History
- Property Details
- And More!
Property Records Guide
- How to Access Property Records in Arizona
- Land Records in Arizona
- What Are Property Records?
- Who Looks Up Arizona Property Records and Why
- Types of Property Records in Arizona
- Buying and Selling Property in Arizona
- How Property Transfer Works in Arizona
- Why Property Values Are Important in Real Estate Transactions
- Arizona Flood Zones
- Local Rules, Timelines & Fees
- Maintaining and Amending Arizona Records
- The Role of the County Recorder
Property Records Guide
- How to Access Property Records in Arizona
- Land Records in Arizona
- What Are Property Records?
- Who Looks Up Arizona Property Records and Why
- Types of Property Records in Arizona
- Buying and Selling Property in Arizona
- How Property Transfer Works in Arizona
- Why Property Values Are Important in Real Estate Transactions
- Arizona Flood Zones
- Local Rules, Timelines & Fees
- Maintaining and Amending Arizona Records
- The Role of the County Recorder